When it comes to navigating the world of auto insurance in Massachusetts, understanding the ins and outs can save you a significant amount of money and stress. Whether you’re a new driver or a seasoned road warrior, knowing how to secure the best rates while fulfilling state requirements is crucial. So, just how much is auto insurance in Massachusetts? Let’s dive into the essentials!
In this guide, we’ll explore the key factors that influence your insurance premiums, uncover opportunities for discounts, and provide expert tips on making smart insurance decisions. Get ready to become an auto insurance pro with advice that packs a punch!


Overview of Auto Insurance in Massachusetts
Here’s a surprising fact: Massachusetts has some of the lowest car insurance premiums in the U.S., but you still need to know the basics. If you’re driving in the Bay State, understanding auto insurance isn’t just helpful—it’s mandatory.
Massachusetts requires all drivers to carry specific types of auto insurance. This includes Bodily Injury to Others, Personal Injury Protection (PIP), and more. But what does this really mean for you?
Basic Requirements for Auto Insurance
First off, every driver in Massachusetts must have liability coverage. This covers damages if you’re at fault in an accident. The minimum limits are $20,000 per person and $40,000 per accident for bodily injury.
The state also mandates Personal Injury Protection, which covers medical expenses regardless of who’s at fault. Plus, you’ll need coverage for damage to someone else’s property.
Pro Tip: It’s always smart to buy more than the minimum coverage to protect yourself fully.
Types of Coverage Available
Beyond the basics, there are various types of coverage you can add. Think Collision and Comprehensive insurance. Collision covers your car if you hit something, while Comprehensive takes care of non-collision events like theft or natural disasters.
There’s also Optional Bodily Injury, which increases your coverage limits, and Uninsured Motorist coverage to protect you against drivers without insurance. Here is the deal: having more coverage options gives you peace of mind.
Obtaining Auto Insurance in Massachusetts
Getting insurance in Massachusetts isn’t rocket science—but it does require some paperwork. Start by comparing quotes from multiple providers. Look for discounts and bundle options.
Next, provide your driver’s license, vehicle registration, and other required documents. Once you choose a provider, they’ll handle the rest—like notifying the Massachusetts Registry of Motor Vehicles.
The Role of the Massachusetts Registry of Motor Vehicles
The RMV plays a crucial part in the state’s auto insurance system. They ensure every vehicle on the road has the necessary insurance coverage. Your provider will electronically notify the RMV when you get or renew your insurance.
If your insurance lapses, you’ll hear from the RMV. And trust me, that’s one call you don’t want to get. Stay insured, stay legal, and keep your driving record clean!
Factors Affecting Auto Insurance Rates

Thinking about how much you pay for auto insurance in Massachusetts? You’re not alone. Auto insurance rates can feel like a mystery, but they’re actually shaped by some concrete factors.
From your driving habits to where you park your car at night, various elements play into the premium you see every month. Some factors are surprising, while others you might expect. Let’s dive into the nitty-gritty of what influences your auto insurance cost in Massachusetts.
Key Factors That Influence Premiums
When it comes to auto insurance premiums, not every driver is created equal. Age, driving history, and the type of vehicle you drive are just the tip of the iceberg. But did you know your credit score and location are just as critical? They can significantly impact your rates.
| Factor | Description | Impact on Rates |
|---|---|---|
| Age | Young drivers typically face higher rates due to lack of experience. | High for young drivers, decreases with age |
| Driving Record | A clean driving record can lead to lower premiums. | High impact if poor, lower rates if clean |
| Vehicle Type | Luxury or sports cars usually cost more to insure. | Higher for expensive or high-performance vehicles |
| Credit Score | Insurers view a high credit score as a sign of responsibility. | Significant impact; lower scores mean higher rates |
| Location | Urban areas with high traffic and crime rates increase risk. | Higher in cities, lower in rural areas |
Significance of Credit Score and Location
Your credit score is more than just a number. It tells insurers how responsible you are with financial matters. The better your score, the lower your rates. Have a low score? You might pay more even if you have a spotless driving record.
Where you live can also play a massive role. If you’re in a bustling city with lots of traffic and accidents, expect to pay more. But if your car resides in a peaceful suburb, you might catch a break. Here’s the deal: location often acts as a marker for risk, so it’s crucial to consider when budgeting for insurance.
Pro Tip: Keep your credit score in check and consider your parking spot as part of your insurance strategy.
Average Cost of Auto Insurance in Massachusetts
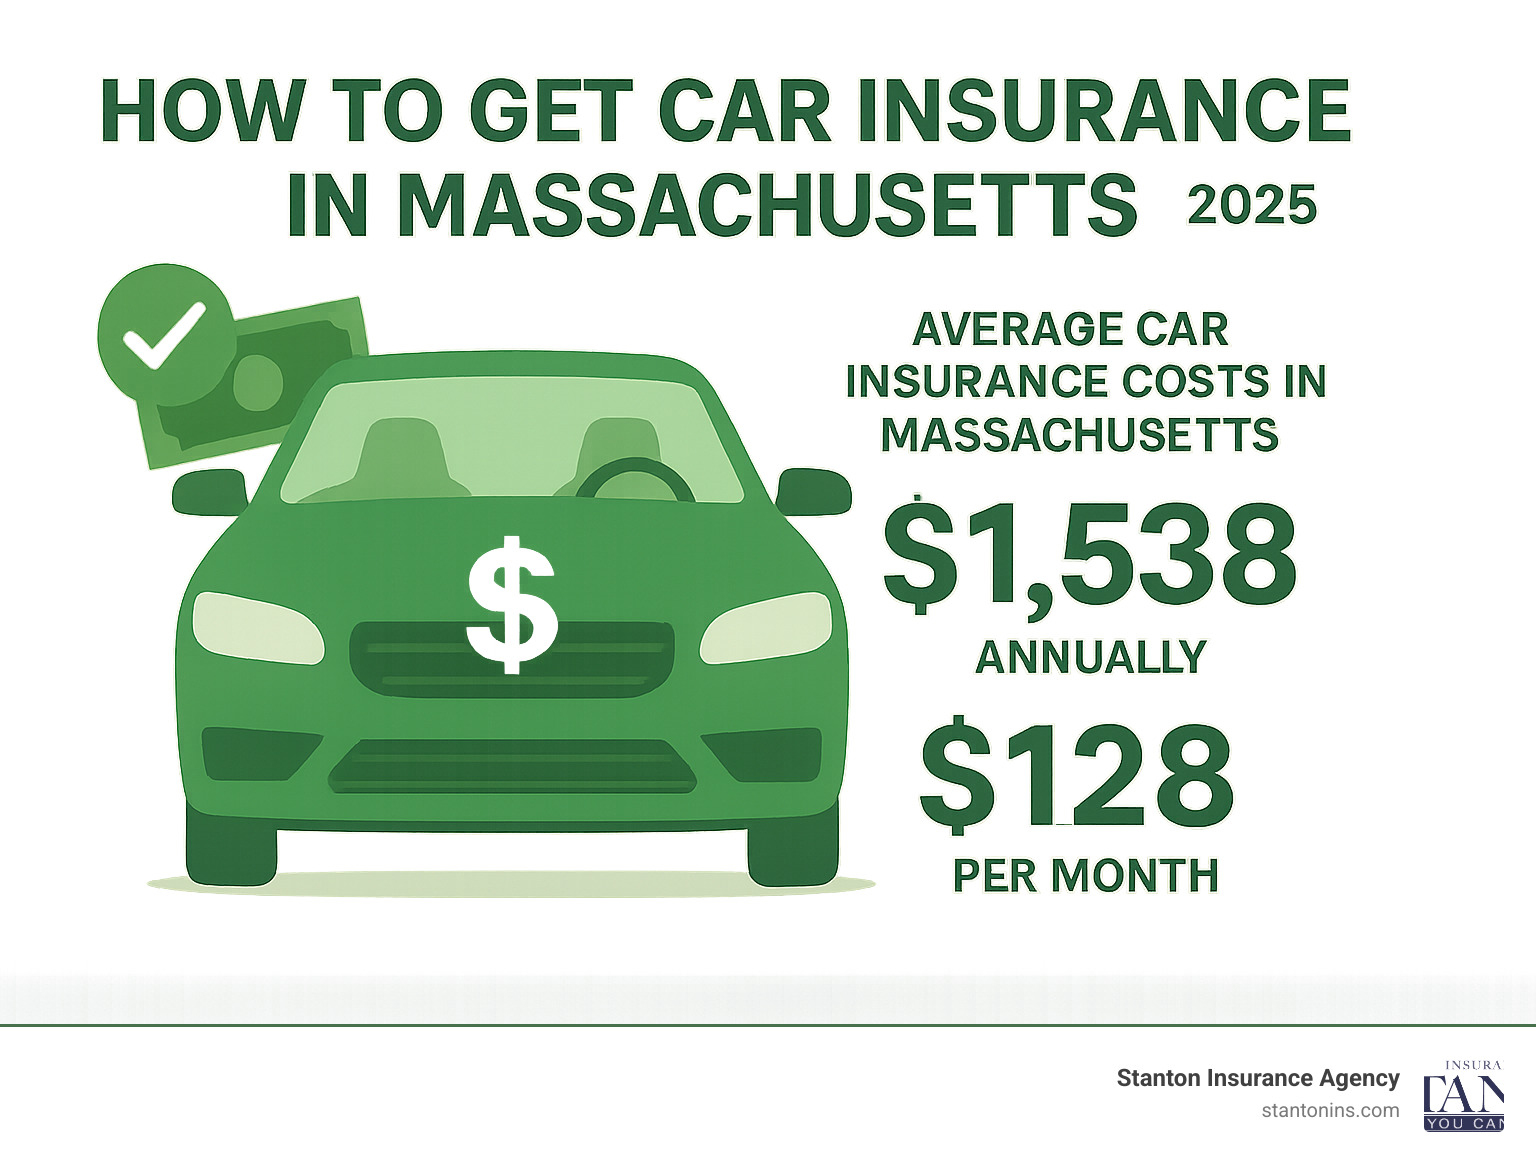
Did you know that Massachusetts isn’t just the home of clam chowder and Red Sox fans? It’s also notorious for its sky-high auto insurance rates. But exactly how much are we talking here?
Here’s the deal: auto insurance in Massachusetts is often higher than the national average. Whether you’re a seasoned driver or a newbie, understanding these costs can save you big bucks. Let’s break it down.
Breakdown of Average Costs by Coverage Type
Massachusetts auto insurance comes in multiple flavors: liability, collision, comprehensive, and more. Each has its own price tag. On average, drivers in the Bay State pay over $1,200 annually for full coverage. Sounds steep, right? But compare that to the national average of roughly $1,000, and you see Massachusetts drivers face a 20% premium. Ouch!
Here’s a quick comparison:
| Coverage Type | Average Cost | Comparison to National Average | Notes |
|---|---|---|---|
| Liability | $600 | +15% | Higher due to dense traffic. |
| Collision | $450 | +25% | Frequent accidents increase costs. |
| Comprehensive | $150 | -5% | Lower thanks to fewer natural risks. |
But wait, there’s more. Recent trends show that these rates are creeping upwards by about 3-5% annually. Yup, inflation and increasing repair costs are squeezing wallets even tighter.
Pro Tip: Regularly compare quotes from different insurers. Loyalty doesn’t always pay in the insurance game.
Discounts and Savings Opportunities
Did you know that you could be paying hundreds less for auto insurance in Massachusetts? The key is to know where to look for discounts and how to qualify for them.
Here’s the deal: insurance companies offer a range of discounts to help you save money. By taking advantage of these opportunities, you can keep more cash in your pocket.
Common Discounts Available to Massachusetts Drivers
Insurance companies in Massachusetts provide a range of discounts that can significantly reduce your premiums. Here are some of the most common ones:
- Good Driver Discount: Maintain a clean driving record, and you could save big.
- Multi-Policy Discount: Bundle your home and auto policies to unlock additional savings.
- Student Discount: Good grades can pay off! Students with high GPAs often qualify for discounts.
- Low Mileage Discount: Drive less? Pay less. If you’re not clocking up the miles, you might be eligible for a lower rate.
- Safety Features Discount: Cars with advanced safety features can lead to discounts.
Methods for Reducing Insurance Costs
Want to slash your insurance bill? Here’s what you can do:
- Shop around and compare rates from multiple providers.
- Increase your deductible to lower your premium.
- Improve your credit score to qualify for better rates.
- Take a defensive driving course to demonstrate your commitment to safety.
How Bundling Policies Can Lead to Savings
Bundling your policies is like a two-for-one deal. By combining your auto insurance with other types of coverage like home or renters insurance, you can enjoy substantial discounts. It’s a simple way to maximize your savings without compromising coverage.
Tips for Maintaining a Good Driving Record
Your driving record is one of the most significant factors in determining your insurance premiums. To keep premiums low:
- Follow traffic laws and avoid tickets.
- Drive safely to prevent accidents.
- Attend advanced driving courses to enhance your skills.
- Pro Tip: Many insurers offer “accident forgiveness” programs. Sign up to avoid premium hikes after your first minor accident.
Legal Considerations and Obligations
Did you know that driving without insurance in Massachusetts can cost you more than your monthly premium? That’s right. The Bay State has some strict auto insurance laws you need to know about.
Here, I’ll break down what you need to do to stay legal and what happens if you slip up.
Mandatory Insurance Requirements
Massachusetts requires all drivers to carry minimum liability coverage. You need at least $20,000 per person and $40,000 per accident in bodily injury liability, plus $5,000 for property damage. But that’s not all! You’ll also need personal injury protection (PIP) and uninsured motorist coverage.
Penalties for Non-Compliance
If you’re caught without coverage, it could lead to hefty fines, license suspension, and even jail time. The fine alone can be up to $5,000! Trust me, it’s not worth the risk. So, make sure you’re covered.
Understanding Insurance Claims
Dealing with insurance claims in Massachusetts? Here’s the deal: report any accident to your insurer right away. The claims process can be straightforward if you have all your documents ready. But, always be honest in your claim to avoid severe penalties down the line.
No-Fault Insurance Rules
Massachusetts operates under a no-fault insurance system. This means your own insurance covers your injuries regardless of who caused the accident. It’s designed to simplify the claims process, but it also affects your ability to sue unless your injuries are severe.
Pro Tip: Always keep a checklist of your insurance requirements in your car. It can save you a lot of headaches down the road.
Resources for Finding Auto Insurance
Shopping for auto insurance in Massachusetts can feel like navigating a maze. There are tons of providers, each promising the best rates and coverage. But how do you find the one that’s right for you?
The key is to leverage the right resources and tools. This guide will walk you through the process, helping you make informed decisions.
How to Shop for Auto Insurance in Massachusetts
Start by listing down what you need in a policy. Do you want comprehensive coverage or just the basics? Knowing your needs will save you from being over-insured. Once you have your list, it’s time to dive into research mode.
Step #1: Use online comparison tools. Websites like NerdWallet and The Zebra can help you compare rates quickly. These platforms allow you to enter your information once and get quotes from multiple providers.
Step #2: Check out local providers too. Sometimes regional companies offer better rates for Massachusetts drivers because they understand the local market better.
Helpful Resources and Tools for Comparing Insurance Providers
Online tools are your best friend here. They streamline the process and give you a clear picture of what’s available. You can also check out customer reviews on sites like Yelp or Consumer Reports to get the scoop on providers’ reputations.
Pro Tip: “Always read the fine print on the policy details before signing up.”
Another great resource is insurance company websites. They often have educational material to help you understand coverage options and benefits.
Steps for Evaluating Insurance Policies Effectively
Evaluating policies is more than just about price. Here’s the deal: you need to consider coverage limits, deductibles, and any additional benefits like roadside assistance or accident forgiveness.
Step #1: Look at the policy coverage options. Is everything you need covered? If not, move on.
Step #2: Evaluate the deductibles. Higher deductibles mean lower premiums, but more out-of-pocket costs if you need to claim.
Step #3: Compare any extras offered. Things like rental car coverage or uninsured motorist protection can make a policy more valuable.
The Role of Insurance Brokers
Insurance brokers can be a game-changer in finding the right policy. They have access to multiple insurance providers and can often secure better rates than you’d find on your own.
A good broker will take the time to understand your needs and tailor their recommendations accordingly. They can also provide valuable insights into which providers have the best reputation for customer service and claims handling.
Remember, brokers work for you, not the insurance companies, so their advice is typically unbiased. Use their expertise to your advantage.
Final Thoughts
In conclusion, understanding how much auto insurance costs in Massachusetts doesn’t have to be a daunting task. With the right knowledge and resources, you can make informed decisions that protect your wallet and your wheels. Whether you’re leveraging discounts or choosing the right coverage for your needs, remember that being proactive and informed is your best strategy. Drive safe and insure smart!
Common Queries
What are the basic requirements for auto insurance in Massachusetts?
In Massachusetts, drivers are required to have liability insurance, personal injury protection (PIP), and uninsured motorist coverage to meet state minimum requirements.
How do factors like age and driving record affect my auto insurance rates?
Age and driving record are significant factors—young drivers often face higher premiums, and a clean driving record can help lower your rates.
What is the average cost of auto insurance in Massachusetts?
The average cost can vary, but typically it’s higher than the national average due to stringent insurance requirements and other regional factors.
Can my credit score impact my auto insurance premiums in Massachusetts?
Yes, insurance companies often consider your credit score when determining rates, as it’s seen as an indicator of risk.
How can I reduce my auto insurance costs in Massachusetts?
Consider bundling policies, maintaining a good driving record, and seeking out available discounts to help reduce your insurance costs.
What penalties exist for not having auto insurance in Massachusetts?
Failing to maintain auto insurance can result in fines, license suspension, and increased insurance premiums once coverage is reinstated.
What are some resources for finding auto insurance in Massachusetts?
Utilize online comparison tools, consult insurance brokers, and review state resources to effectively compare and select the best insurance options.