When it comes to navigating the world of insurance in North Carolina, understanding the intricate factors that determine your rates is crucial. Whether you’re a lifelong resident or new to the Tar Heel State, finding the best insurance rates in NC can save you a significant amount of money. In this comprehensive guide, we’ll break down everything you need to know to ensure you’re getting the best deal possible.
With a unique blend of state-specific regulations and industry trends, securing affordable insurance in North Carolina requires a strategic approach. From understanding the regional rate variations to leveraging discounts and incentives offered by top providers, this guide will equip you with the essential knowledge to make informed decisions. Let’s dive in and explore how you can ensure optimal insurance rates in NC!


Understanding Insurance Rates in North Carolina
Did you know that the average car insurance rate in North Carolina is significantly lower than the national average? That’s right, but why is this the case?
Understanding why your insurance rates are what they are starts with knowing the factors that affect them specifically in North Carolina. From state regulations to regional variances, several elements come into play.
Factors Affecting Insurance Rates in NC
Let’s break down the key factors that influence insurance rates in North Carolina. First, your driving record plays a massive role. If you’re a safe driver, you’re in luck. BUT if you have a history of accidents or violations, expect higher rates.
Another crucial factor is the type of vehicle you drive. High-performance cars typically come with high insurance rates. Here is the deal: even your credit score can affect your insurance premiums in NC.
State Regulations Impacting Insurance in NC
North Carolina has some unique regulations that impact insurance rates. The state employs a rate bureau that sets a base rate for policies. This ensures that rates don’t skyrocket, which is good news for you.
However, insurers can apply for rate deviations, meaning your actual rate might differ. Keep in mind, North Carolina is one of the few states that require uninsured motorist coverage. This requirement can also influence your rates.
Insurance Rate Trends in NC Over the Past Decade
Over the last ten years, insurance rates in NC have shown a steady increase. BUT compared to the national trend, North Carolina has managed to keep a more stable trajectory.
Here’s how it looks:
| Year | NC Average Rate | National Average Rate |
|---|---|---|
| 2013 | $790 | $1,100 |
| 2018 | $870 | $1,230 |
| 2023 | $950 | $1,370 |
Average Insurance Rates by Region in NC
Insurance rates can vary drastically depending on where you live in North Carolina. Let’s take a closer look:
| Region | Average Rate |
|---|---|
| Charlotte | $1,100 |
| Raleigh | $1,000 |
| Asheville | $950 |
| Wilmington | $900 |
Pro Tip: Always compare rates from multiple providers within your region to ensure you’re getting the best deal possible.
Top Insurance Providers in North Carolina
Looking for the best insurance providers in North Carolina? You’re in the right place! Finding the right provider can make a huge difference to your coverage and wallet.
But with so many options out there, it’s easy to get overwhelmed. Here is the deal: I’ve narrowed down the top insurance providers in NC to help you make an informed decision.
Leading Insurance Companies in North Carolina
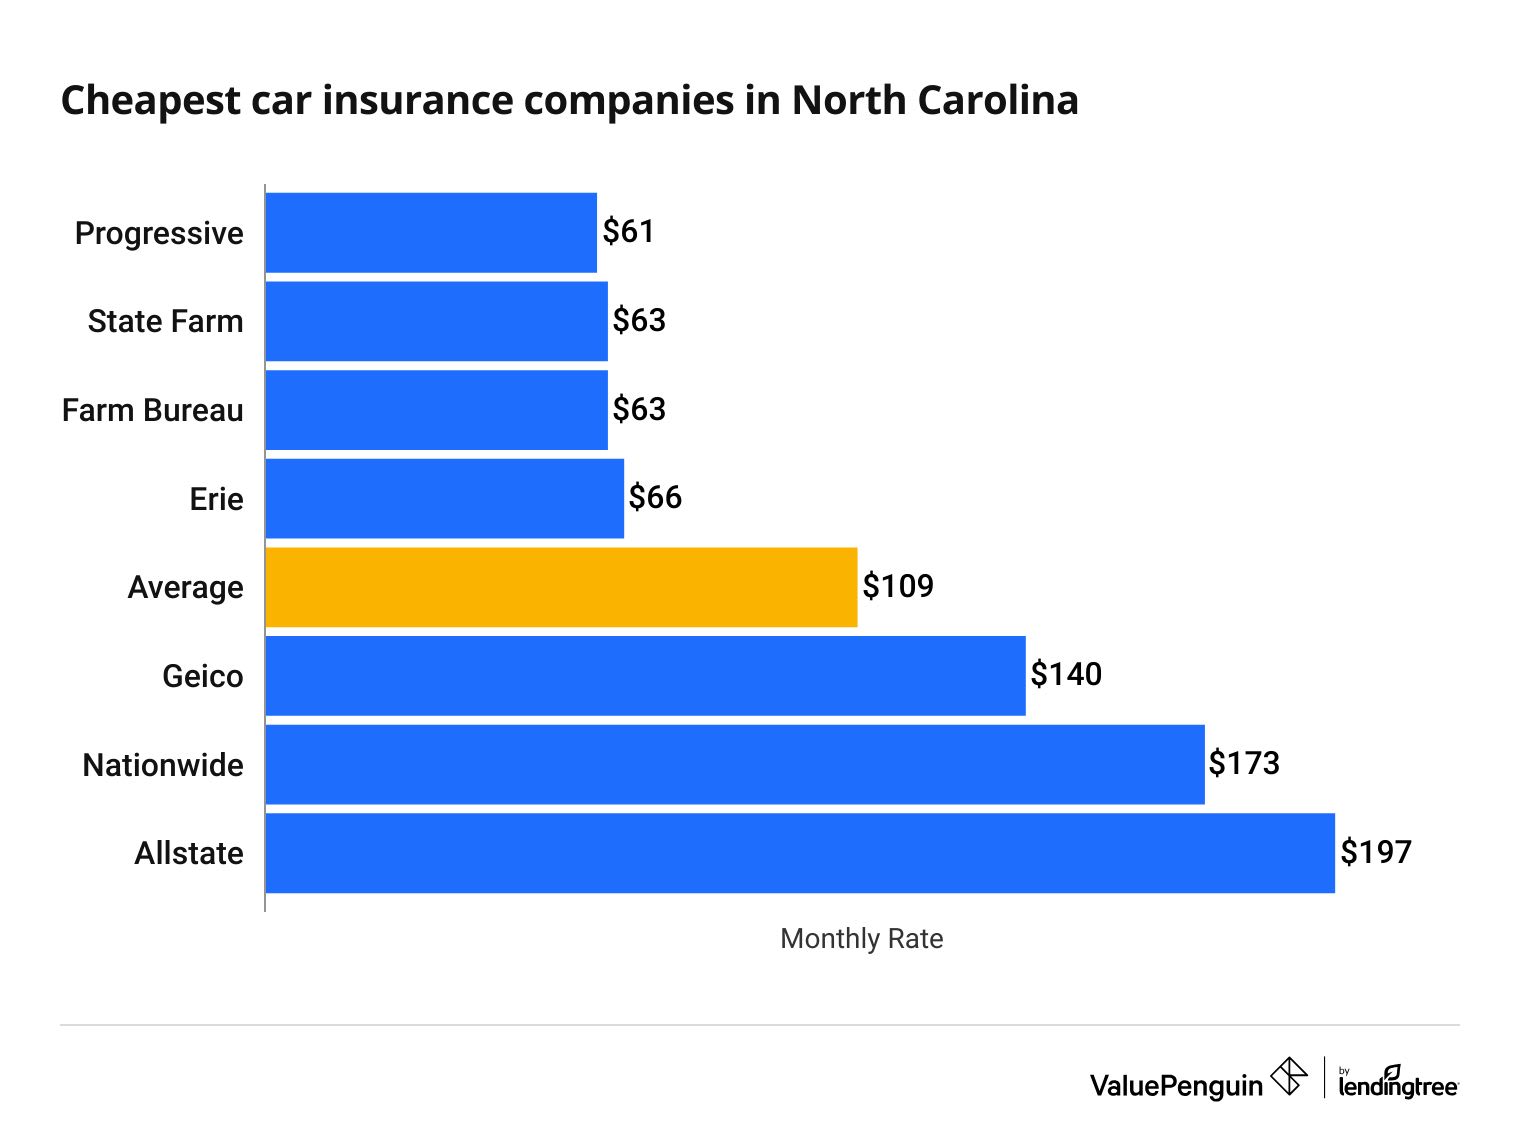
When it comes to insurance in North Carolina, a few companies consistently stand out from the rest. State Farm, for instance, is widely known for its strong customer service and extensive agent network. Nationwide offers a range of discounts and customizable policies. Allstate is loved for its accident forgiveness program and USAA shines for military families with its excellent customer satisfaction.
Unique Offerings of Top Providers
Each of these insurers has unique offerings that make them popular choices. State Farm provides a personal touch with its local agents. Nationwide is a go-to for tech-savvy clients with its easy-to-use mobile app. Allstate’s accident forgiveness can be a game-changer if you have a less-than-perfect driving record. USAA offers competitive rates and perks for veterans and their families.
Comparison of Services and Pricing
Let’s break down how these top providers stack up against each other.
| Provider | Key Services | Average Pricing |
|---|---|---|
| State Farm | Strong local presence, agent network | $$ |
| Nationwide | Customizable policies, tech-friendly | $$$ |
| Allstate | Accident forgiveness, diverse coverage options | $$$ |
| USAA | Military focus, high satisfaction | $$ |
Pro Tip: Always compare quotes from at least three providers to find the best deal.
Consumer Ratings and Reviews
What do people say? According to customer reviews, State Farm scores high for availability and support. Nationwide users often praise their digital tools. Allstate’s accident forgiveness is frequently mentioned in glowing terms. And USAA? Well, it’s hard to find a negative review among military families!
Strategies for Finding the Best Insurance Rates
Think you’re paying too much for insurance in North Carolina? You’re probably right. The truth is, many people overpay because they don’t know the right strategies.
But don’t worry, I’ve got you covered. Here’s how you can start saving on your insurance rates today.
Effective Methods for Shopping Around in NC
Shopping for insurance isn’t as painful as you think. The first step is to get multiple quotes. You’d be shocked at how much rates can differ from one company to another. Use online comparison tools to gather quotes from at least three different providers.
Next, don’t forget to research each company’s reputation. A lower rate might mean lower quality service. Check reviews and ratings to ensure you’re getting a good deal without compromising service quality.
Mastering Negotiation Tactics
Did you know you can negotiate your insurance rate? Here’s the deal: most people don’t even try. Call your provider and ask for a discount. It’s easier than you think.
Use competitive rates you’ve found as leverage. Simply tell them, “I’ve got a better offer from another provider.” You’ll be amazed at how quickly they start offering discounts or bundling options.
Comparing Quotes Effectively
When it comes to comparing quotes, it’s not just about the price. Look at what each policy offers. Here’s a simple table to help you analyze different aspects:
| Provider | Monthly Premium | Deductible | Coverage Options | User Reviews |
|---|---|---|---|---|
| Provider A | $150 | $500 | Comprehensive, Collision | 4.5/5 |
| Provider B | $130 | $1,000 | Liability Only | 3.8/5 |
| Provider C | $180 | $250 | Full Coverage | 4.2/5 |
The Benefits of Working with Insurance Brokers
Working with a broker can save you both time and money. Brokers have access to multiple policies and can find you the best deal based on your specific needs. They often get better rates than you would on your own!
Pro Tip: Let the broker do the heavy lifting. Provide them with your budget and coverage requirements, and they’ll hunt down the best options for you.
Plus, brokers can negotiate on your behalf, and they know the ins and outs of the industry. This ensures you not only get a great rate but also the right coverage for your situation.
Discounts and Incentives for Lower Insurance Rates
Want to save money on your insurance? You’re in luck! Many insurance providers in North Carolina offer a variety of discounts and incentives to help you score lower rates. Let’s dive into how you can take advantage of these savings.
Here’s the deal: insurance companies offer a multitude of discounts. But not everyone knows how to find or qualify for them. Understanding these could mean the difference between overpaying and getting a steal on your insurance policy.
Common Discounts Available for Insurance in NC
Many insurers provide discounts if you fit certain criteria. These discounts can apply to a wide array of factors, such as your driving record, vehicle type, or even your loyalty to the insurer.
- Safe Driver Discount: Keep your record clean and save big.
- Multi-Policy Discount: Bundle home and auto for additional savings.
- Good Student Discount: For young drivers maintaining a high GPA.
- Low Mileage Discount: Drive less, pay less.
Pro Tip: Always ask your agent about any hidden discounts you might qualify for!
How Bundling Policies Can Reduce Rates
Insurance companies love when you keep all your business with them. If you have multiple policies, consider bundling them. This not only simplifies your bills but it can also lead to substantial discounts!
For instance, bundling your auto and home insurance might save you anywhere from 10% to 25%. That’s a significant cut on your overall premium costs. Plus, it keeps everything organized under one roof.
Eligibility Criteria for Various Discounts
Here’s a quick checklist to see if you’re eligible for some common discounts. Make sure you tick as many boxes as possible to maximize your savings.
- Clean driving record for at least 3 years.
- Owns multiple policies with the same provider.
- Full-time student with a GPA of 3.0 or higher.
- Annual mileage is below 7,500 miles.
- Has not filed a claim in the past 3 years.
Incentives Offered by Providers to Attract New Customers
Ever wondered why new customers get the best deals? Insurance companies often provide sweet incentives to attract fresh clients. Whether it’s a discounted first-year rate or a gift card, these perks can make switching providers worthwhile.
Look out for sign-up bonuses, such as a free month of coverage or a reduced deductible for your first year. These incentives are designed to make the transition seamless and financially beneficial. If you’re considering a switch, it might pay to ask what’s on offer for new customers!
Impact of Personal Factors on Insurance Rates
Did you know that personal factors can make or break your insurance rates in North Carolina? Understanding these factors could save you a ton of money, and I’m here to show you how.
In North Carolina, your insurance rates aren’t just numbers pulled from thin air. They’re based on you—who you are, what you drive, and even how you handle your finances. Let’s dig deeper.
Influence of Age and Driving History on Rates
Let’s face it: if you’re young, insurers might consider you a risk. In fact, drivers under 25 often face premiums that are up to 50% higher than older drivers. BUT, here’s the deal: a clean driving history can lower those rates significantly. Traffic violations and accidents? They’ll send your rates soaring.
Credit Score’s Effect on Insurance Premiums
Surprise! Your credit score isn’t just for loans. It can play a huge role in determining your insurance rates. Those with a higher credit score often land better rates because insurers see them as financially responsible. So, improving your credit can give you a much-needed break on costs.
Vehicle Type and Usage in Rate Determination
Driving a flashy sports car? Expect higher insurance rates. Why? High-performance vehicles are seen as riskier to insure. Conversely, a safe, reliable sedan that you use for commuting might earn you lower premiums. It’s not just what you drive, but how you drive it.
Pro Tip: Opt for a car with advanced safety features. Insurers love these and might reward you with discounts.
Demographic Analysis of Insurance Rates in NC
North Carolina’s demographics can also affect insurance rates. Here’s a snapshot:
| Demographic Factor | Effect on Rates |
|---|---|
| Urban vs. Rural | Urban areas tend to have higher rates due to increased traffic and accident risk. |
| Age Group (Under 25 vs. Over 50) | Younger drivers face higher rates; older, experienced drivers often benefit from discounts. |
| Income Level | Higher income may lead to better credit scores, potentially lowering rates. |
Future Trends in Insurance Rates in North Carolina
Did you know that insurance rates in North Carolina could see a shift due to emerging trends? From technology breakthroughs to economic upheavals, several factors are poised to influence your insurance premiums. Let’s dive into what the future might hold for insurance rates in the Tar Heel State.
Changes in the insurance landscape are not just speculation. They’re unfolding as we speak. And if you want to stay ahead, it’s crucial to understand these evolving dynamics.
Technological Advancements Impacting Insurance Pricing
Technology is reshaping the insurance industry faster than you can say “self-driving cars.” With the rise of data analytics and artificial intelligence, insurers can now assess risk more accurately than ever. This means precision pricing based on individual risk profiles rather than generalized categories.
Consider telematics, for instance. These are devices that monitor your driving habits in real-time, leading insurers to offer personalized rates tailored to your driving behavior. BUT, are you ready to have your driving tracked for a discount?
Pro Tip: Embrace technology. Using telematics could save you big on your premiums.
Economic Factors Influencing Future Rates
Economic conditions have always played a significant role in determining insurance rates. In North Carolina, factors like inflation, unemployment rates, and economic growth can all lead to changes in how much you pay for insurance. For example, a stronger economy could increase vehicle ownership, leading to higher traffic, and potentially more accidents.
Here is the deal: when the economy fluctuates, so do insurance rates. Keeping tabs on economic indicators can give you a heads-up on whether you’ll be shelling out more or less for insurance in the near future.
Scenario Analysis of Future Rate Trends
Let’s play out a few scenarios. Imagine a future where self-driving cars dominate the roads. Insurance rates as we know them could plummet because of fewer accidents. Conversely, if climate change results in more severe weather patterns, homeowners in North Carolina might face hefty premium hikes.
These scenarios highlight the potential volatility in future insurance rates. It’s not all doom and gloom, though. With every challenge comes an opportunity for savings if you’re prepared to adapt.
Forecasting Potential Rate Changes
Forecasting insurance rates is like predicting the weather—uncertain but necessary. Analysts predict that by 2030, insurance could be more affordable for low-risk individuals due to better risk assessment technologies. BUT higher-risk individuals might see their rates skyrocket as insurers become more adept at pinpointing risky behavior.
Stay savvy and proactive. Understanding these trends will empower you to make informed decisions about your insurance, potentially saving you money in the long run.
Conclusion
As you embark on the journey to find the best insurance rates in NC, remember that knowledge is your most powerful tool. By staying informed about the factors influencing rates, the top providers in the state, and strategic ways to negotiate and compare options, you’re setting yourself up for success. Keep these insights in mind, and you’ll be well on your way to securing insurance that not only meets your needs but also respects your budget. Here’s to smart shopping and savvy savings!
FAQ
What factors affect insurance rates in North Carolina?
Insurance rates in North Carolina are influenced by factors such as age, driving history, credit score, vehicle type, and usage, as well as state regulations and regional variations.
How can I find the best insurance rates in NC?
To find the best insurance rates in NC, compare quotes from multiple providers, use negotiation tactics, and consider working with insurance brokers for expert advice.
What are common discounts available for insurance in NC?
Common discounts include good driver discounts, multi-policy discounts, and discounts for safety features or low mileage.
How does my credit score affect my insurance premiums?
In North Carolina, a higher credit score can lead to lower insurance premiums, as it is often seen as an indicator of financial responsibility.
What role does vehicle type play in insurance rates?
The type of vehicle you drive affects your insurance rate. Generally, vehicles with higher safety ratings and lower repair costs are cheaper to insure.
How can bundling policies reduce my insurance rates?
Bundling multiple policies, such as home and auto insurance, with the same provider can lead to substantial discounts on your rates.